PA home insurance discounts: Save More on Your Luxury Home Coverage
Luxury homes in Pennsylvania come with premium price tags, which means your insurance costs can climb fast. The good news is that PA home insurance discounts exist specifically for high-value properties, and many homeowners miss out on substantial savings.
We at Eric L. Ash Insurance Agency help luxury homeowners find every discount available, from bundling policies to installing advanced security systems. This guide shows you exactly where those savings hide and how to claim them.
Where Luxury Homeowners Find the Biggest Discounts
Bundle Policies for Immediate Savings
Combining your home insurance with auto or life coverage ranks among the fastest ways to reduce your overall insurance costs. Bundle policies for multi-line discounts can save you up to $1,429 when combining auto and home insurance. An independent agency like Eric L. Ash Insurance Agency can match your luxury home with the insurer offering the strongest bundling incentives for your specific situation. The key involves comparing what each carrier actually delivers rather than assuming all bundling discounts perform equally. Some insurers bundle aggressively on home coverage while others prioritize auto discounts, so the math changes based on your needs.
Security Systems Pay for Themselves Within Months
Installing monitored alarm systems, smart locks, and surveillance cameras qualifies you for immediate discounts that typically range from 5% to 20% on your annual premium. A professionally monitored system costs between $30 and $50 monthly but can reduce your home insurance bill by $100 to $300 per year, meaning the security investment pays for itself within months. High-value properties benefit even more because insurers view loss prevention as non-negotiable on luxury homes.
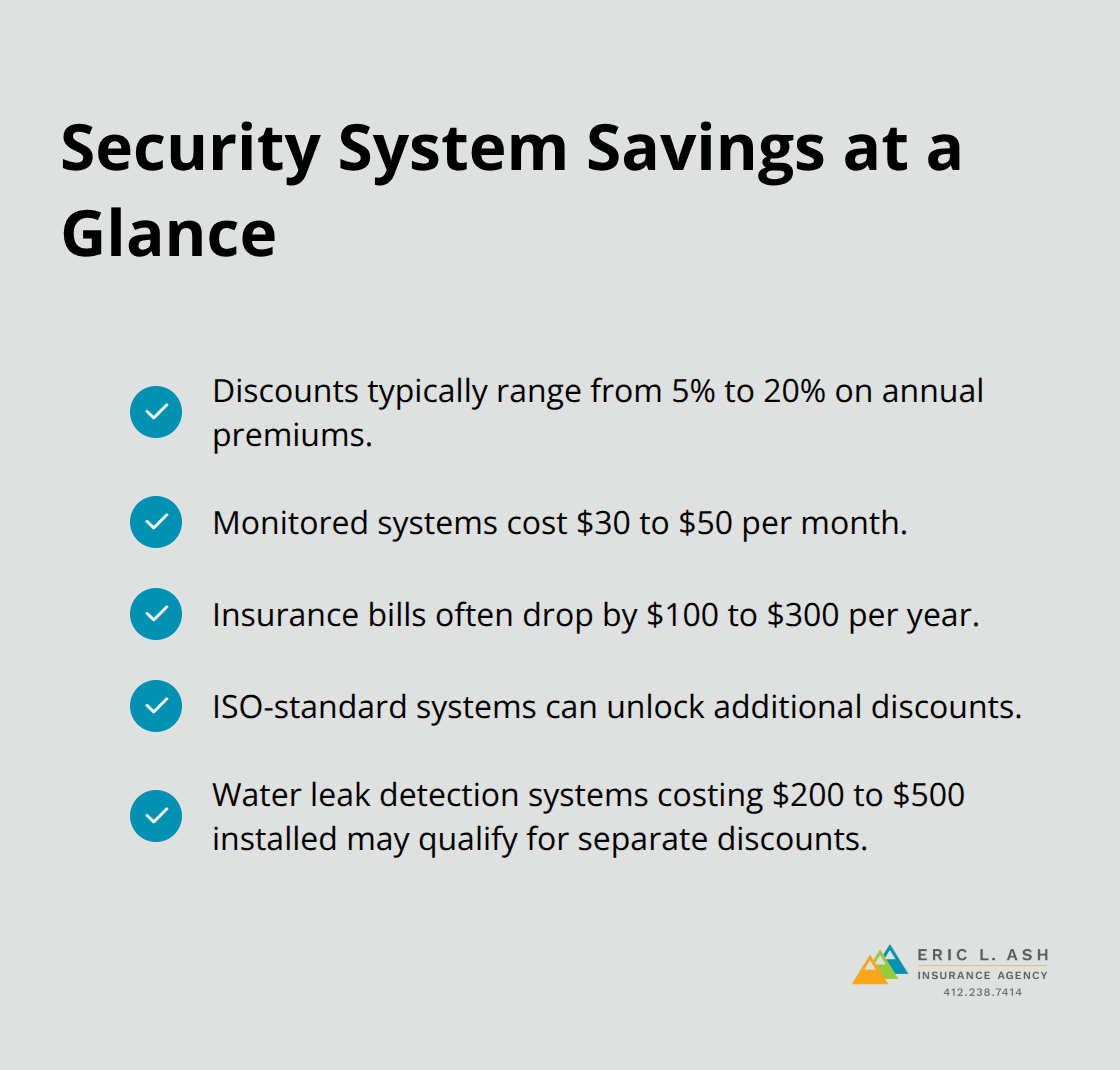
Systems meeting Insurance Services Office standards trigger additional discounts that standard systems don’t provide. Water leak detection systems (which cost $200 to $500 installed) often qualify for separate discounts since water damage represents one of the largest claim categories in Pennsylvania.
Structural Upgrades Lower Your Premium Immediately
Updating your roof, electrical system, or plumbing directly impacts your insurance costs. A roof replacement within the last 10 years typically qualifies for a 5% to 15% discount because newer roofs resist weather damage and fire better than aging ones. Impact-resistant roofing materials can increase your discount to 20% or higher in some cases. Pennsylvania homeowners who install backup generators, modernize HVAC systems, or upgrade to fire-resistant materials should notify their agent immediately (these improvements often trigger premium reductions you won’t receive unless you request them). The timing matters significantly-waiting to mention these upgrades means paying full price for months or years after the work is complete.
Your property improvements and security choices form only part of the savings equation. The coverage limits you select and how often you review them determine whether your luxury home actually stays protected as your property value changes.
What Coverage Limits Actually Protect Luxury Homes
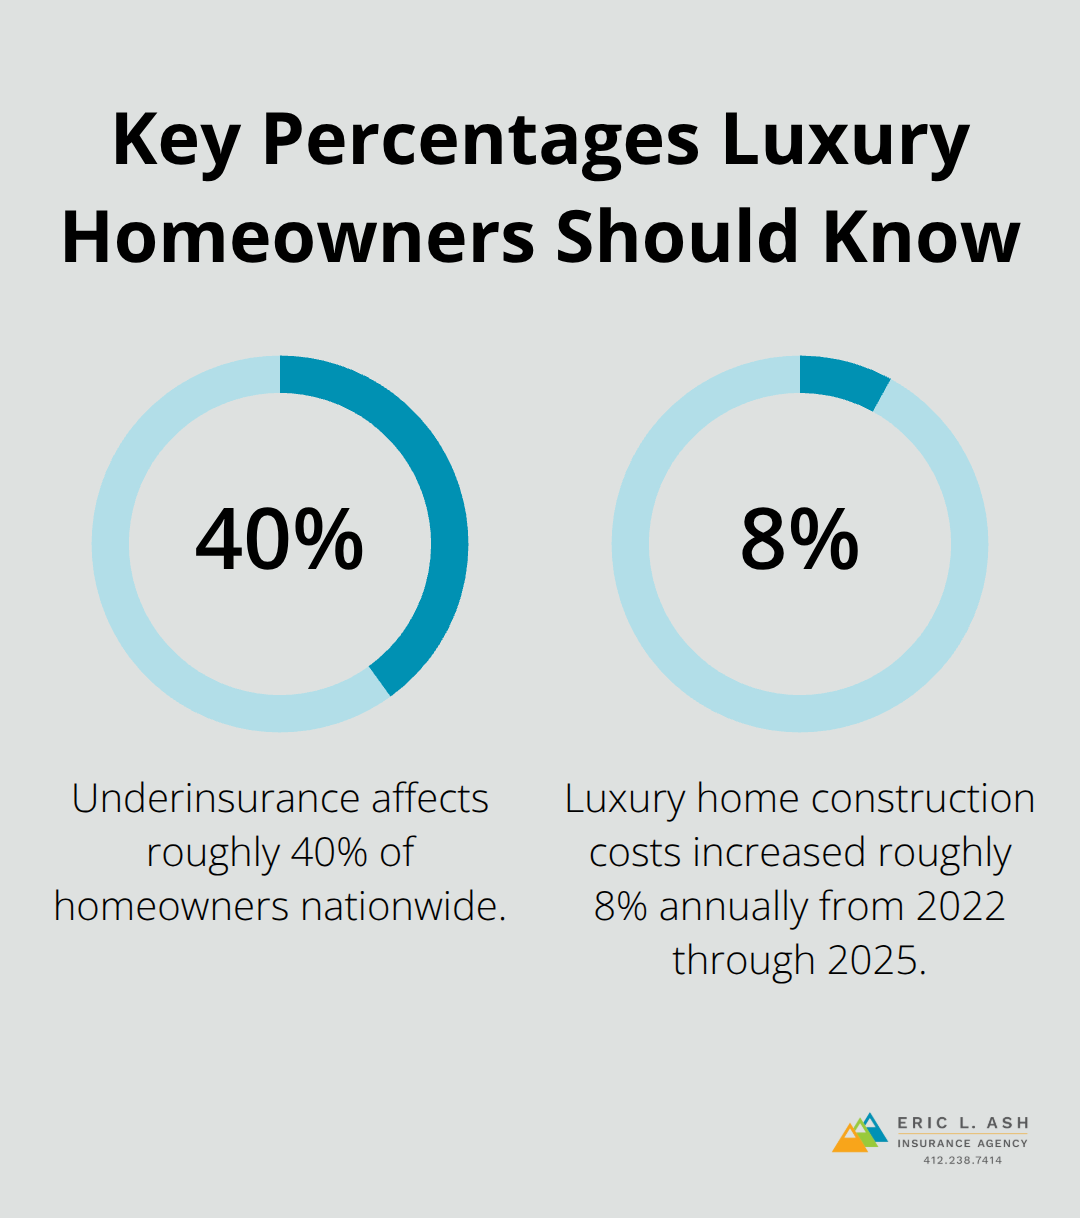
Luxury homes in Pennsylvania typically cost $500,000 to $2 million or more, yet many homeowners set replacement cost limits based on outdated property assessments or rough estimates. The National Association of Insurance Commissioners reports that underinsurance affects roughly 40% of homeowners nationwide, and luxury properties face even greater risk because construction costs for high-end finishes, custom materials, and specialized systems run significantly higher than standard home repairs. Setting your replacement cost limit requires calculating what it would actually cost to rebuild your exact home from the ground up, including granite countertops, hardwood flooring, smart home systems, and architectural details.
Pennsylvania contractors typically charge $150 to $250 per square foot for luxury home construction, compared to $100 to $130 for standard homes, so a 5,000-square-foot luxury property needs $750,000 to $1.25 million in replacement coverage alone. Many insurers now offer extended replacement cost endorsements that cover 125% to 150% of your stated limit, which protects you if construction inflation or unforeseen structural issues increase your actual rebuilding costs beyond your initial estimate.
Specialized Coverage for Art, Jewelry, and Collections
Standard homeowners policies cap coverage for jewelry, artwork, and collectibles at $1,500 to $2,500 total, which means a single piece can wipe out your entire limit. Luxury homeowners need scheduled personal property endorsements that list high-value items individually with their appraised values, and these endorsements typically cost $50 to $150 per year per item depending on replacement value. Wine collections, rare books, fine art, and jewelry require appraisals from certified professionals, and most insurers require updated appraisals every three to five years as market values fluctuate. Homeowners who own items worth $10,000 to $500,000 or more should work with agents who understand how to structure proper coverage without gaps. Some carriers offer blanket coverage for entire collections if you provide documentation, which simplifies administration compared to scheduling each item separately.
Finding Agents Who Understand Luxury Property Complexity
Standard insurance agents often lack experience with high-value homes, specialty items, and the specific risks luxury properties face in Pennsylvania. Independent agencies that work with multiple carriers can match your property with insurers who specialize in luxury coverage and understand that your $800,000 home needs fundamentally different protection than a $300,000 property. Agents experienced with luxury homes ask detailed questions about your property’s age, construction materials, roof condition, and security systems during the underwriting process, which directly impacts your rates and coverage options. Your agent should proactively identify underinsurance gaps and recommend appropriate coverage limits rather than simply processing whatever you request. Pennsylvania homeowners benefit from working with agents who maintain ongoing relationships with carriers’ luxury underwriting teams, because those connections often lead to better rates and faster claims resolution when issues arise.
The coverage limits you select form only part of your protection strategy. High-value items sitting inside your home require their own specialized attention, and knowing how to structure that coverage separates homeowners who recover fully from claims versus those who face significant out-of-pocket losses.
How to Lock in the Lowest Rates on Luxury Coverage
Review Your Coverage Limits Annually
Your coverage limits need annual review because property values in Pennsylvania shift yearly, and what protected your home adequately three years ago might leave you significantly underinsured today. The Insurance Information Institute found that homeowners who review their coverage annually catch underinsurance gaps an average of 18 months faster than those who ignore their policies. Schedule this review in January or whenever your policy renews, then ask your agent for a detailed breakdown of what your replacement cost limit actually covers versus what it would cost to rebuild today.
Request updated construction cost estimates from local Pennsylvania contractors because luxury home construction costs increased roughly 8% annually from 2022 through 2025, meaning a property that needed $800,000 in coverage two years ago might require $920,000 today. Your agent should also recalculate coverage for any high-value items you acquired, since that diamond ring purchased last year or the art collection you inherited won’t appear on your original policy.
Claim Discounts You’ve Already Earned
Many homeowners discover during their annual review that their loss prevention systems qualify them for additional discounts they never claimed. Ask specifically about security system upgrades, roof replacements, or structural improvements made since your last policy anniversary. Insurers often fail to apply these discounts automatically, which means you leave money on the table unless you request them directly.
Shop Multiple Carriers for Better Rates
Shopping multiple carriers represents the single most effective way to reduce your luxury home insurance costs, yet most homeowners accept their renewal quote without checking alternatives. Request quotes from at least three insurers that specialize in high-value properties, because luxury coverage pricing varies dramatically between carriers-one insurer might quote $2,400 annually while another charges $3,100 for identical coverage on the same property.
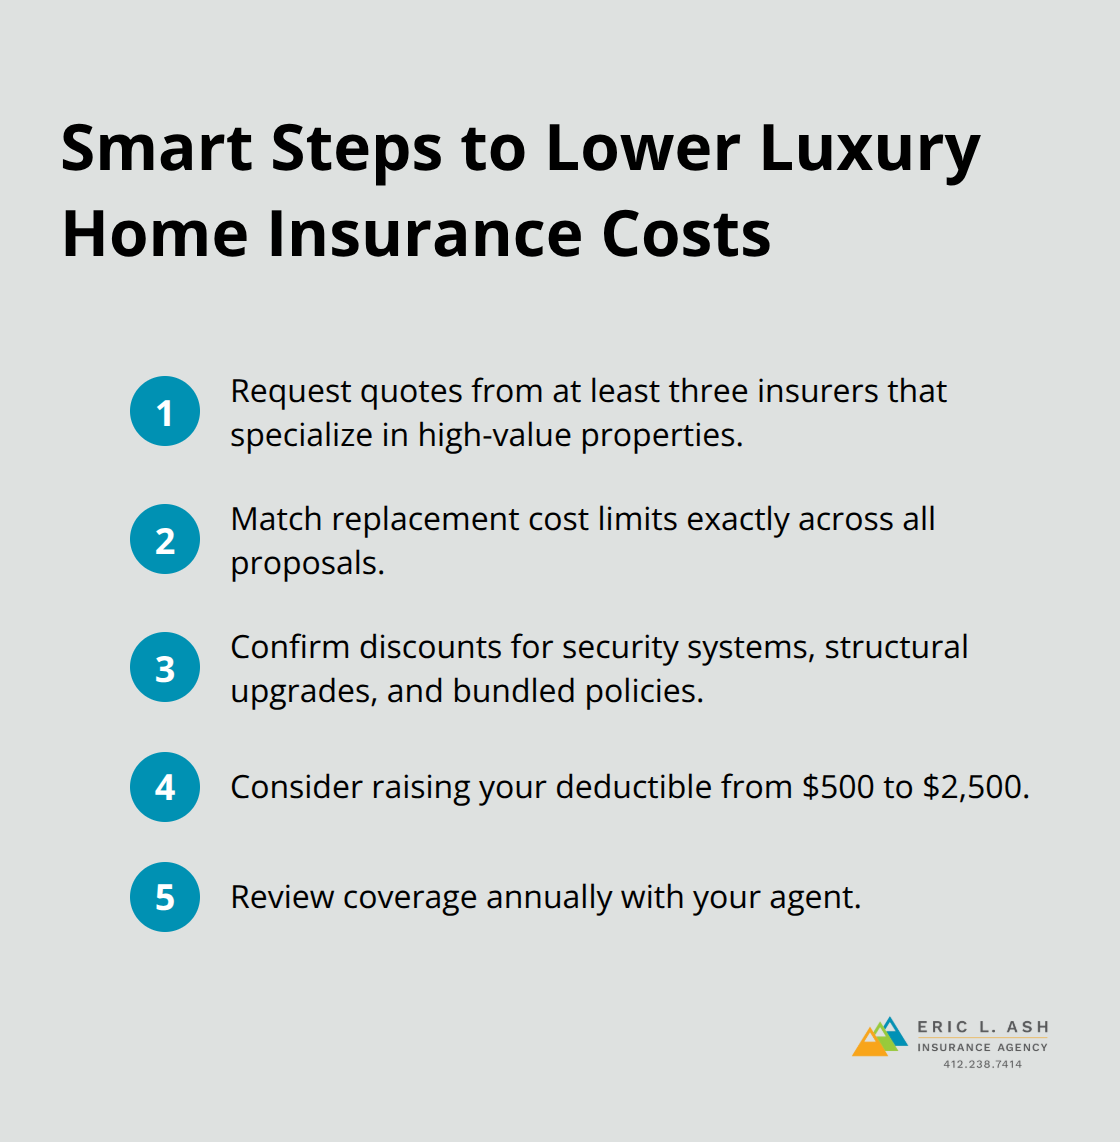
When comparing quotes, verify that replacement cost limits match exactly across all proposals, since some carriers set lower limits by default and inflate your premium accordingly. Ask each insurer specifically about discounts for loss prevention systems, structural upgrades, and bundled policies, because some carriers apply these discounts automatically while others require you to request them.
Leverage Independent Agency Advantages
An independent agency maintains relationships with dozens of carriers and can shop your specific luxury property across multiple markets simultaneously, saving you hours of individual phone calls while identifying rate options you wouldn’t find alone. Compare not just the premium but the deductible options available, since raising your deductible from $500 to $2,500 typically reduces your annual premium by 15% to 25%, which makes sense if you have adequate emergency savings to cover a claim without financial stress.
Final Thoughts
Pennsylvania luxury homeowners who actively pursue PA home insurance discounts typically save $1,500 to $3,000 annually compared to those who accept standard rates. The three core strategies work together: bundling policies across multiple lines, installing loss prevention systems that qualify for immediate discounts, and reviewing coverage limits annually to match your actual property value. Structural upgrades like roof replacements and modernized electrical systems trigger additional savings that many homeowners never claim because they fail to notify their agent about completed work.
Your coverage limits deserve the most attention because underinsurance on a luxury property means facing substantial out-of-pocket costs after a major claim. Pennsylvania construction costs for high-end homes run $150 to $250 per square foot, so calculating accurate replacement costs requires input from local contractors rather than guesswork. Specialized endorsements for jewelry, art, and collections prevent the $1,500 to $2,500 standard policy limits from leaving you exposed on individual valuable items.
Shopping multiple carriers remains non-negotiable for luxury homeowners since premium quotes vary by $700 to $1,000 or more for identical coverage. An independent agency eliminates the tedious work of contacting dozens of insurers individually while identifying rate options and discount combinations you wouldn’t discover alone. Contact Eric L. Ash Insurance Agency to receive personalized quotes that reflect every discount your property qualifies for.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.